
Built for commercial closings.
Most lending software is built around the credit decision. Prodeal is built around the closing, the multi-party checklist grind that turns an approved loan into a funded one with a clean record.
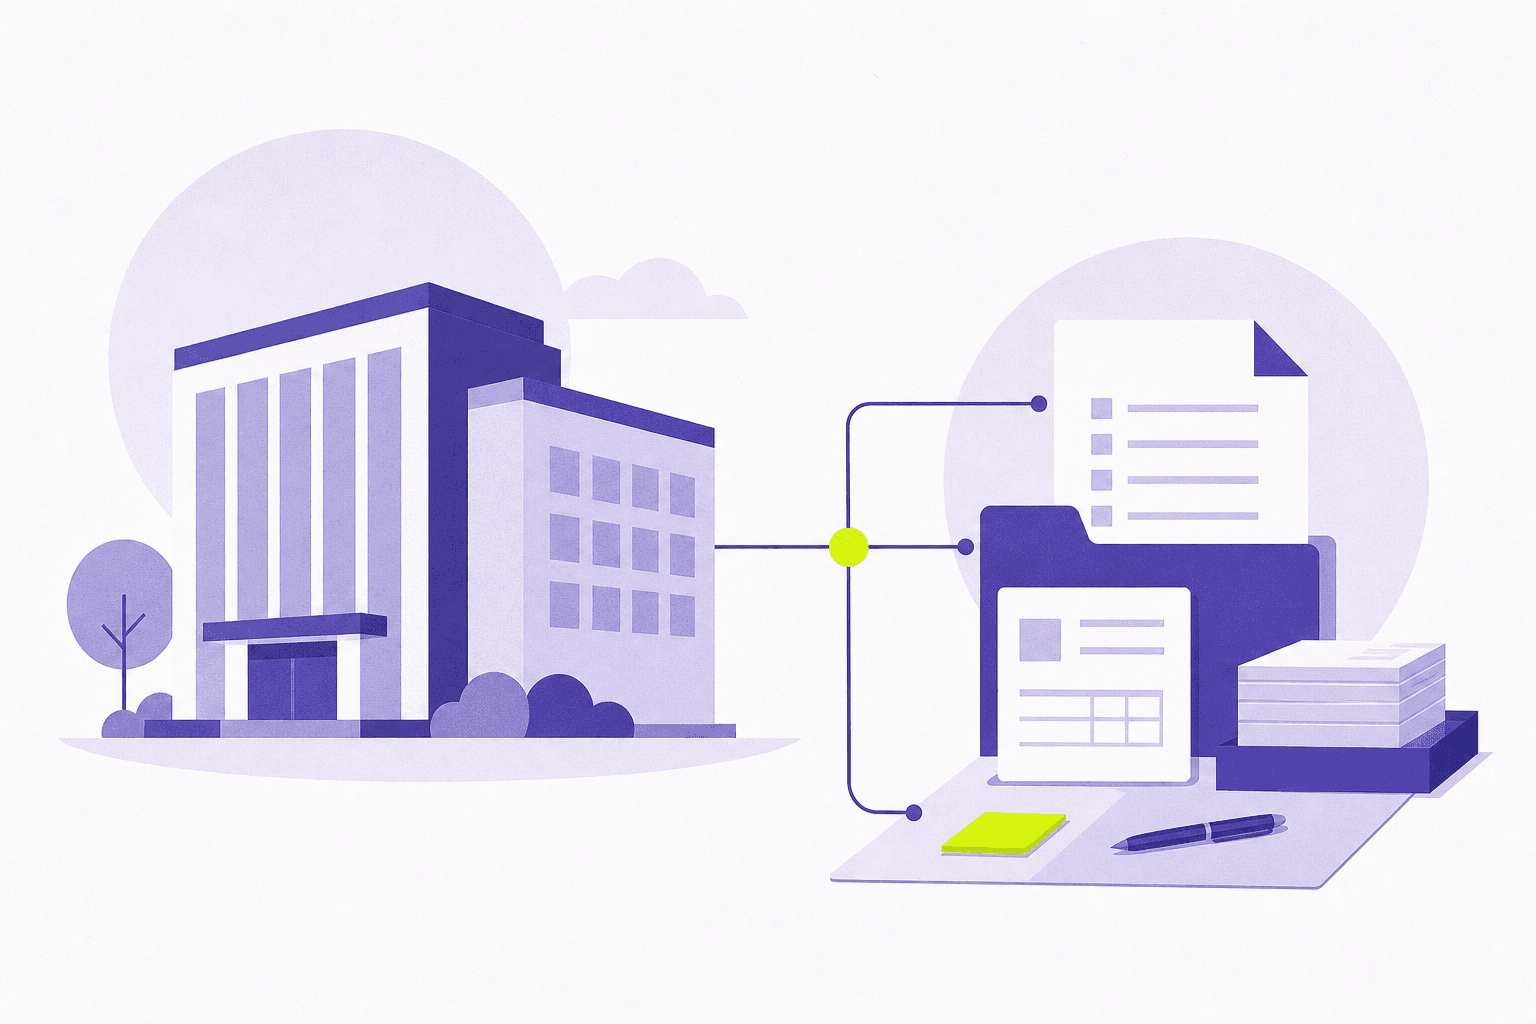
Commercial loan software covers several layers that are often confused: origination and underwriting, closing, document management, and servicing. A loan origination system decides the credit. A servicing system administers the loan after funding. Prodeal is the layer between them, where conditions are cleared, documents are collected from outside parties and the closing binder and audit record are built.
The four layers people call commercial loan software
The phrase covers an origination system that underwrites and approves, a closing layer that clears conditions and collects documents, a document management system that stores the file, and a servicing platform that administers the loan after funding. Vendors in each layer describe themselves with the same words, which is why evaluations start confused.
The practical way to tell them apart is to ask which moment the product owns. An origination system owns the decision. A servicing platform owns the payment stream and the covenant calendar. A document system owns retrieval. The closing layer owns the weeks between approval and funding, and it is the only one of the four whose users include people who do not work for the lender.
Most banks already own two or three of these. The gap is usually the closing layer, which is why it tends to be run on a spreadsheet long after everything else has a system.
Which layer to fix first
Fix the layer where your days are going rather than the one with the loudest category. If approvals are slow, the problem is upstream in credit. If exceptions pile up after funding, the problem is the closing record and what it deferred. If nobody can find a document from two years ago, the problem is retrieval.
The reason the closing layer is often the right first move is that it compounds in both directions. A complete closing produces a clean file for servicing and a shorter exception list at exam, and it does it without changing the credit process or the core system.
It is also the layer that touches the borrower, which makes it the part of the stack a customer actually experiences.
Trusted by leading Real Estate Teams
Generic tools miss the closing
CRMs, LOS platforms, and shared drives each handle a piece and leave the closing in email.
Commercial deals are multi-party
Borrower, counsel, title, and vendors all owe items into one deadline.
The record has to last
Commercial loans are audited, serviced, and assumed for years.
Commercial closings, one room.
A multi-party commercial loan runs from approval to funding.
01Open from your template
The commercial document set and structure land in place when the deal opens.
02Bring every party in
Borrower, counsel, title, and insurance work the same room, built for external parties.
03Status moves as work happens
Items carry an owner, a due date, and a live status the whole deal reads.
04Keep a lasting record
The audit trail and closing binder export for servicing and the exam.
Run one commercial closing through it.
Book a demoBuilt for the commercial close
Schedule B, estoppels, participations, draws. The vocabulary of the desk, not a generic project tool.
Multi-party by default
Borrower, counsel, title, and insurance in one room with scoped access, because that is the shape of the deal.
The whole book, visible
Every commercial deal in flight on one filterable view.
A record that lasts
Commercial loans are audited and serviced for years. The file exports complete.
Questions lenders ask
- What is commercial loan software?
- Software built for the commercial closing specifically: the multi-party request list, the document flow, and the audit trail that turn an approved loan into a funded one with a durable record.
- Why not use a generic project tool?
- Generic tools track tasks but not the closing: the documents, the external parties, and the record. Prodeal is built for the commercial deal itself.
- Does it handle multi-party deals?
- Yes. Borrower, counsel, title, and insurance work the same room with scoped access, which is the normal shape of a commercial closing.
- Will the record hold up for an exam?
- Yes. Every action is time-stamped and exportable, and the closing binder assembles from the deal, so the file is exam-ready.
- Is an origination system the same thing?
- A loan origination system handles application through approval. Commercial loan software is the broader phrase, covering origination, closing, document management and servicing. Asking which moment a product owns, and who outside the bank logs into it, separates them quickly.
- Do we have to replace the core banking system?
- The closing layer does not. It sits between credit approval and the core, and hands the funded loan and its complete file across. Replacing a core is a different project with a different risk profile, and it is rarely what a slow closing calls for.
- What matters most when a credit union buys this?
- The same things any lender should, with examination in mind. Member business lending draws NCUA attention to documentation and monitoring, so the ability to produce the file and the activity history years later carries more weight than feature count.
Your next commercial close, on one list.
Bring one live deal to the walkthrough. See the room built on your own checklist.